Fire Insurance for Manufacturing Units: High‑Risk Coverage Explained

7 Views
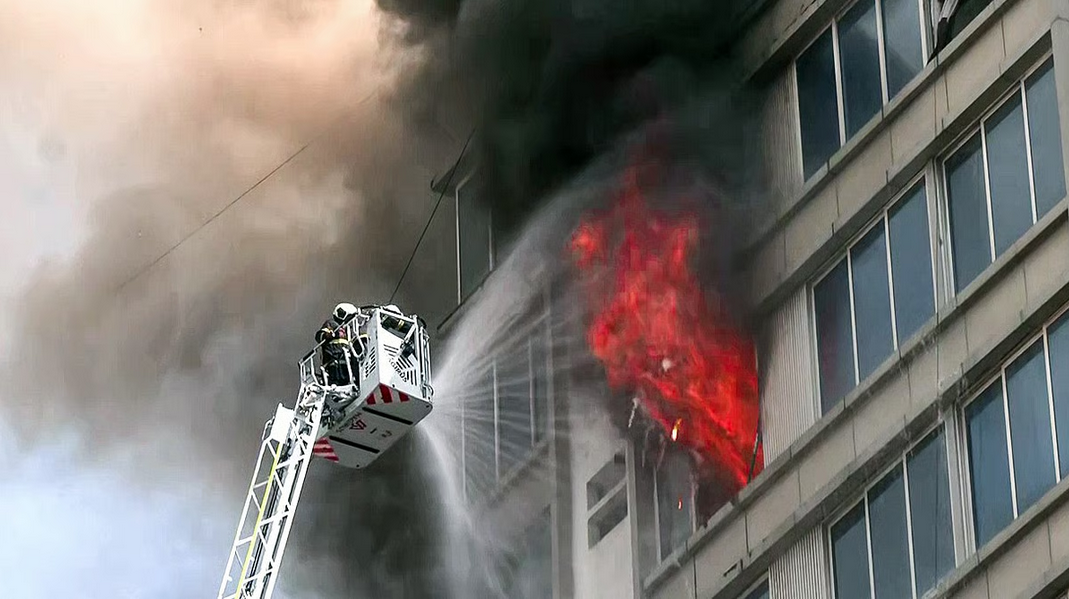
Manufacturing units bring together many of the conditions that make fires likely and costly: heat, electrical loads, flammable materials, dust, stored stock and expensive machinery, often under one roof. When a fire breaks out, the damage rarely stops at the building. Production halts, orders are missed and customers may turn elsewhere. Understanding how fire insurance treats manufacturing risks helps owners choose cover that matches the scale of what’s at stake.
Why Factories Are Treated as Higher Risk
Insurers price fire cover according to occupancy, meaning what the premises are used for. Manufacturing processes involving chemicals, plastics, textiles, paper, wood, oils or high temperatures generally carry higher fire risk than offices or warehouses holding non-combustible goods.
Premiums for fire insurance for manufacturing units also reflect the building’s construction, the quantity and nature of stock, the distance between buildings and the fire protection available. Two factories in the same industry can receive very different quotes depending on how well they manage these factors.
Which Product Applies
The right product depends on the total value at risk at one location. Units with assets up to ₹5 crore generally fall under Bharat Sookshma Udyam Suraksha, and those between ₹5 crore and ₹50 crore under Bharat Laghu Udyam Suraksha. Larger units usually buy a Standard Fire and Special Perils policy or a customised product.
These policies typically cover buildings, plant and machinery, furniture and fittings, and stock against fire, lightning, explosion, storm, flood, riot and other listed perils, subject to policy terms. Earthquake cover is included in the Bharat products and may be an add-on under other policies.
Offices Within the Factory Premises
Many manufacturing sites include administrative blocks, design studios or sales offices. These areas house computers, records and furniture that also need protection, and they’re usually included in the overall site policy.
Where a business has separate administrative premises away from the plant, it may arrange fire insurance for Office locations as a separate cover. Office risks are generally lower than factory risks, so separating them can sometimes help the business get premiums that reflect each location’s actual exposure.
Covering Stock and Machinery Properly
Stock levels in manufacturing units often change through the year. A declaration policy or floater cover can help match insurance to fluctuating stock values, rather than insuring at peak levels all year or risking underinsurance at busy times. These options vary by product.
Machinery should be insured at a value that reflects the cost of replacement. Reinstatement value cover, where available, pays the cost of replacing with new equivalent items rather than a depreciated value, subject to conditions such as actually reinstating the property.
Business Interruption Cover
For a factory, the biggest loss after a fire is often lost production. Fire loss of profits cover, also called business interruption cover, helps replace lost gross profit and pay ongoing fixed costs, such as salaries, rent and loan interest, while operations are restored.
Choosing the right indemnity period, meaning how long the cover will pay after a loss, is critical. Consider how long it would realistically take to rebuild, replace specialised machinery and regain customers.
Fire Safety and Your Premium
Investment in fire protection can influence what you pay. Sprinklers, hydrant systems, detection and alarm systems and trained fire response teams reduce the chance of a small fire becoming a major loss, and some insurers recognise approved systems through premium discounts.
Ask your insurer which protection measures they take into account and what standards apply. Keep maintenance records up to date, because surveyors may check whether systems were working at the time of a loss.
Exclusions and Limits to Understand
Fire policies generally exclude wilful acts by the insured, wear and tear, gradual deterioration, and electrical or mechanical breakdown of machinery itself, unless a resulting fire spreads. Spontaneous combustion and fermentation may be excluded or covered only under certain conditions, which matters for units storing materials like coal or agricultural produce.
Each claim usually carries an excess, and underinsurance can reduce payouts in proportion. The Bharat Sookshma and Laghu Udyam products waive underinsurance up to 15 per cent, but larger shortfalls still matter. Read the policy wording and the Customer Information Sheet carefully.
Common Mistakes Manufacturers Make
Underinsuring stock and machinery is a common error, often because values haven’t been updated after expansion. Another is failing to inform the insurer about changes in processes or materials, which can alter the risk and affect claims.
Weak fire safety practices also cause trouble. Poor housekeeping, blocked exits, unserviced extinguishers and overloaded wiring increase risk, and surveyors may examine them after a loss. Good records of stock, maintenance and safety audits make claims far smoother.
Choosing the Right Cover
Start with an accurate valuation of buildings, machinery and stock at each location. Identify the main fire hazards in your processes and the protection in place, and share this information with your insurer.
Consider business interruption cover alongside property cover, and review both every year. As your operations grow and change, your cover needs to keep pace.
A factory fire can destroy years of work in hours, but the right cover can shorten the road back. Matching your policy to the real risks of your operations is what makes that recovery possible.
